Tax calculator Armenia: property pays 10% of the sale price when a business buys, shares and crypto pay nothing
Armenia has no capital gains tax. A sale falls under the personal income tax, and the Tax Code gives each kind of asset its own rule: property sold to a company, an individual entrepreneur or a notary pays 10% of the price under article 150(9), a developer pays 20% under article 150(11), and shares, land, sales to a private individual and, since 2025, ordinary crypto are deducted from income under article 149, article 147(1)(38), article 147(1)(16) and article 147(1)(16.1). Salary and every other income without its own rate pays the flat 20% of article 150(1).
Work out the tax on a share, crypto, fund or property disposal from your dates and prices. Enter sales by hand or import your CSVs, and the calculator splits multi-parcel sales under FIFO, applies the buyer and construction tests, and shows the arithmetic behind the final figure. Everything stays in your browser.
Rates current as of 2026-09-19, from the Republic of Armenia Tax Code and the sources each record cites.
Income tax
How a sale fits into Armenia's income tax
Armenia taxes a resident on gross income from sources in and outside the country (article 141(1)(1)). The tax base is that income less the deducted income that article 147 lists (article 143(1)(1)). A sale is one more income in that sum, and the Code gives each kind of sale its own rate or its own deduction.
Income that no later part of article 150 rates separately, salary included, pays the general rate of article 150(1): a flat 20%, with no bands. It was 23% in 2020, 22% in 2021 and 21% in 2022, and has been 20% since 1 January 2023. No sale on this page pays the general rate. Each one lands in one of these cases:
- Property sold to a company, an individual entrepreneur or a notary: 10% of the price (article 150(9)).
- Property sold by a developer: 20% of the price (article 150(11)).
- Property sold to a private individual: deducted (article 147(1)(16)). Land is deducted whoever buys it (article 147(1)(38)).
- Shares, fund units and unlisted participation: deducted (article 149(1)(2) and (3)).
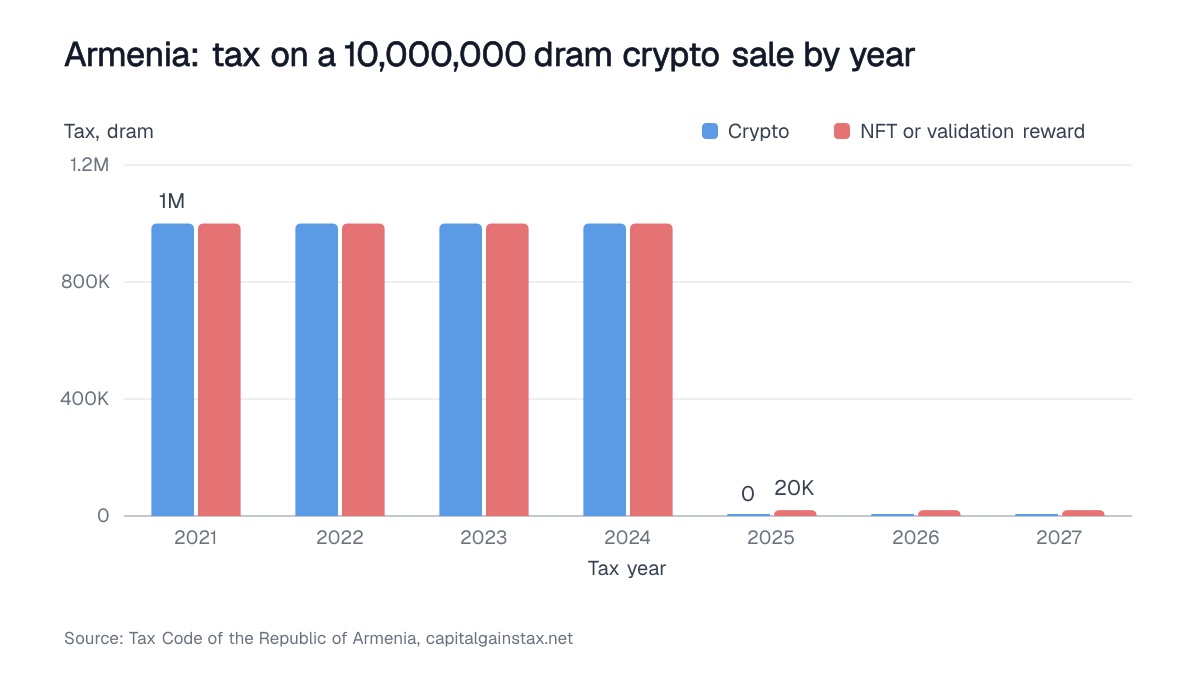
- Ordinary crypto: deducted since 1 January 2025 (article 147(1)(16.1)). NFTs and validation rewards pay 1% (article 150(9.1)).
Gold sold to a gold-market agent (article 147(1)(39)) and a motor vehicle sold to a VAT payer holding a trade-in licence (article 147(1)(41)) are deducted too.
Property
Selling property in Armenia: the buyer decides the tax and the price is the base
Article 150(9) charges 10% on the total income received from the alienation of property. The base is the price, not the profit: the tax base is gross income less the deductions in article 147 (article 143(1)(1)), and what you paid for the property is not on that list. A sale below your purchase price pays the same 10% of what you receive as a sale at a profit.
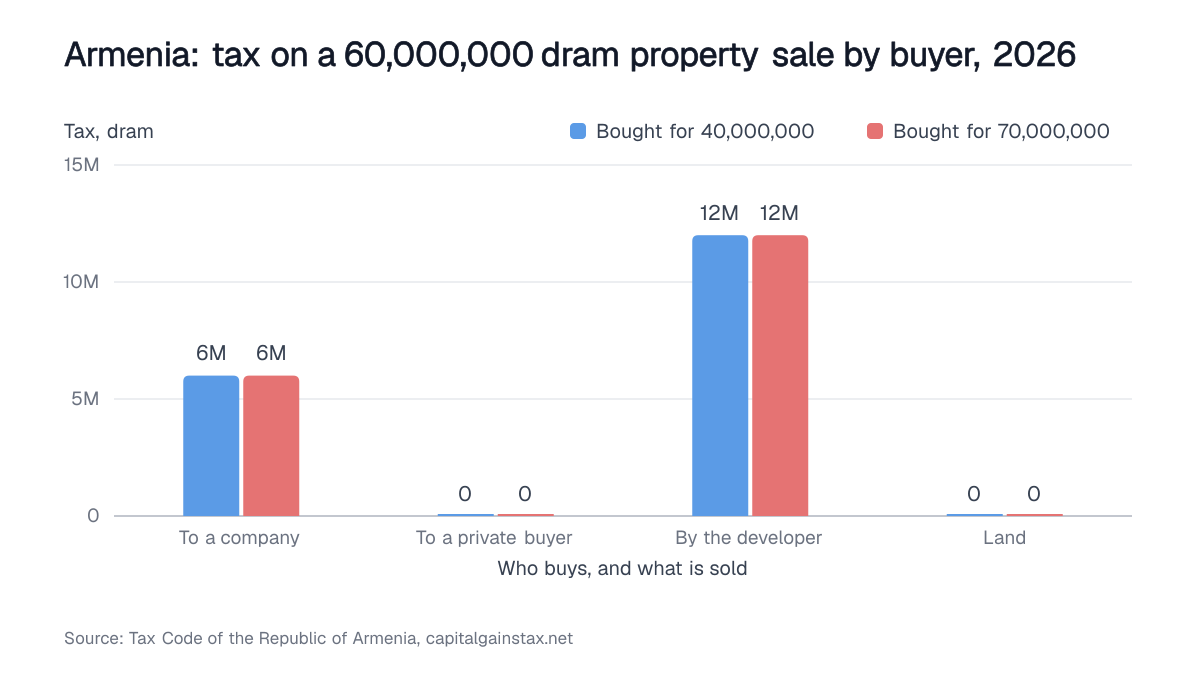
Who buys decides whether the tax applies at all. Article 147(1)(16) deducts income from the alienation of property received from a natural person who is not an individual entrepreneur or a notary, so a sale to a private individual pays nothing. A company, an individual entrepreneur or a notary as buyer brings the 10% back. Land is deducted whoever buys it, whatever its designated purpose (article 147(1)(38)).
In the example a flat bought 6 years earlier for AMD 40,000,000 sells for AMD 60,000,000 in 2026, a profit of AMD 20,000,000. Sold to a company, the tax is AMD 6,000,000, 30% of the profit. The identical sale to a private individual pays AMD 0.
Rates used: 10% from article 150(9) and the buyer deduction in article 147(1)(16) of the Tax Code.
Example: a flat bought for AMD 40,000,000 and sold for AMD 60,000,000 in 2026
| Step | Amount |
|---|---|
| Purchase price | AMD 40,000,000 |
| Sale price | AMD 60,000,000 |
| Profit | AMD 20,000,000 |
| Tax if a company, an individual entrepreneur or a notary buys (10% of the price) | AMD 6,000,000 |
| Tax if a private individual buys | AMD 0 |
Show the code
Copy this code into your page. The chart and the credit both link to this page.
Developers
A developer's sale pays 20%, on a price that cannot fall below 80% of the cadastral value
Article 150(11) sets 20% on income from the sale of a building, its apartments or other premises by a constructor. Article 145(1)(1) covers a natural person who is the constructor of a multi-apartment building, a subdivided building or a private residential house and sells to another natural person: the income is the actual price, or 80% of the immovable property tax base (the cadastral value) when there is no price or the price is lower.
The private-buyer deduction does not reach these sales. Article 147(1)(16) states that a developer's sale of a building, apartments or other premises to a private individual is not deducted income.
In the example a developer sells an apartment for AMD 70,000,000 against a cadastral value of AMD 100,000,000. The floor is AMD 80,000,000, so the tax is AMD 16,000,000. On the price alone it would be AMD 14,000,000, and the AMD 55,000,000 the developer spent building the apartment changes neither figure.
Rates used: 20% from article 150(11) and the 80% floor from article 145(1)(1) of the Tax Code.
Example: a developer sells an apartment for AMD 70,000,000 in 2026, cadastral value AMD 100,000,000
| Step | Amount |
|---|---|
| Construction cost | AMD 55,000,000 |
| Sale price | AMD 70,000,000 |
| Income taxed (80% of the cadastral value) | AMD 80,000,000 |
| Tax at 20% | AMD 16,000,000 |
| Tax if the price alone were taxed | AMD 14,000,000 |
Shares and funds
Shares, funds and unlisted stakes in Armenia: the gain is deducted income
Article 149(1)(2) and (3) deducts income from participation in an organisation's authorised or share capital (stock, share, unit), from other securities that prove an investment, and from investment-fund securities, including their sale or exchange. For these sales the article does not separate listed from unlisted holdings and sets no holding period, so a share sold a week after you buy it is deducted the same as one held for ten years.
In the example shares bought 3 years earlier for AMD 20,000,000 sell for AMD 50,000,000 in 2026. The AMD 30,000,000 gain pays AMD 0.
One exception depends on what the stake is in. Article 149(2)(3) removes the deduction when the participation was formed through a building, apartment, private house or other construction (unfinished ones included) and you sell it in the tax year you acquired it or in the 3 tax years after. That income pays 10% (article 150(15)). The test counts tax years, not days: a stake acquired in 2023 and sold in 2026 pays AMD 1,500,000 on a gain of AMD 15,000,000, while the same stake acquired in 2022 passed its last taxable year, 2025, and pays AMD 0.
Rules used: the deduction in article 149(1)(2) and (3) and the exception in article 149(2)(3) of the Tax Code.
Example: shares bought for AMD 20,000,000 and sold for AMD 50,000,000 in 2026
| Step | Amount |
|---|---|
| Purchase price | AMD 20,000,000 |
| Sale price | AMD 50,000,000 |
| Gain | AMD 30,000,000 |
| Tax | AMD 0 |
Crypto
Crypto tax in Armenia: ordinary crypto sales are deducted since 1 January 2025
Law HO-499-N of 4 December 2024 put the current crypto rules in force from 1 January 2025 to 31 December 2031 (the note to article 150). Article 147(1)(16.1) deducts income from the alienation of a crypto-asset, so the sale of an ordinary crypto-asset pays nothing.
Two kinds stay taxable. Crypto-assets that are unique in essence and not replaceable (NFTs), and crypto-assets created automatically as a reward for maintaining a distributed ledger or validating transactions, are carved out of the deduction by article 147(1)(16) and pay 1% under article 150(9.1).
For 2021 to 2024 the calculator reads a crypto sale as a sale of property under article 150(9): 10% of the proceeds, not of the gain. In the example a coin bought for AMD 5,000,000 and sold for AMD 18,000,000, a gain of AMD 13,000,000, pays AMD 0 in 2026 and AMD 1,800,000 in 2024.
Rules used: the deduction in article 147(1)(16.1), the 1% rate in article 150(9.1) and the property rate in article 150(9) of the Tax Code.
Example: a coin bought for AMD 5,000,000 and sold for AMD 18,000,000
| Step | Amount |
|---|---|
| Gain | AMD 13,000,000 |
| Tax if sold in 2026 | AMD 0 |
| Tax if sold in 2024 | AMD 1,800,000 |
Show the code
Copy this code into your page. The chart and the credit both link to this page.
Traps
The rules that catch sellers out
Six rules cost Armenian sellers more than the rates do.
- A loss does not lower a property tax. Property sold to a business is taxed on the price (article 150(9)), so a sale below your purchase price still pays 10% of what you receive.
- A developer's sale to a private individual is taxed, not deducted (article 147(1)(16)), and a price under 80% of the cadastral value is lifted to that floor (article 145(1)(1)).
- A stake formed through a construction is taxed when sold in the acquisition year or the 3 tax years after (article 149(2)(3)). The window counts tax years, so a stake bought in December and one bought in January of the same year have the same last taxable year.
- A share's gain is deducted, a dividend is not. Dividends pay 5% (article 150(8)) unless the stock is listed on the exchange operating in Armenia, where dividends received from 1 March 2020 to 31 December 2027 are deducted (article 149(1)(4)) and other dividends are not (article 149(2)(4)).
- A car sold to a company pays 10% of the price unless the company is a VAT payer holding a trade-in licence (article 147(1)(41)).
- The sale date decides the crypto rule. A coin sold the day before 1 January 2025 and the same coin sold on that day fall under different rules (note to article 150).
Changes
What changed in Armenia's rules on sales, 2021 to 2027
The property rates did not move in these years. Every record from 2021 to 2027 carries 10% on property sold to a business, 20% on a developer's sale and a deduction for securities, land and private-buyer sales. The 2027 record carries the year before it forward and is a planning year.
The general rate fell: 22% in 2021, 21% in 2022 and 20% from 1 January 2023 (article 150(1)). It does not touch sales, but it moves the tax on salary and other income in the same declaration.
Crypto changed on 1 January 2025. Ordinary crypto sales became deducted income under article 147(1)(16.1), and NFTs and validation rewards took the 1% rate of article 150(9.1). The rules run to 31 December 2031 (the note to article 150).
Declaring changed. For the 2023 and 2024 reporting years only listed groups declared, among them public officials and people who borrowed AMD 20,000,000 or more in the year (article 156(4.1)). From the 2025 reporting year every resident citizen declares, and Law HO-324-N of 24 October 2025 added article 156.1, under which the tax authority completes the declaration first.
One window closes. Dividends on stock listed on the exchange operating in Armenia are deducted only if received by 31 December 2027 (article 149(1)(4)).
Filing and paying
Declaring and paying the tax on a sale in Armenia
The annual income tax declaration is filed from 2 March to 1 July of the year after the sale (article 156(4)(2)), and the tax is paid by 1 July (article 158(2)(2)). Sales made in 2026 are due by 1 July 2027.
From the 2025 reporting year every resident who is a citizen of Armenia declares (article 156(4.1)), and deducted income received from family members is not declared. The tax authority completes the declaration first from the data it holds, you can amend it inside the same window, and a completed declaration you leave alone counts as submitted (article 156.1).
Tax Code, article 150
Armenia income tax on property, shares and crypto sales
Rates by asset and buyer, year by year (article 150 of the Tax Code)
| Tax year | Securities & funds | Property to a business | Developer sale | Property to a private individual | Land | Crypto | NFT & validation rewards |
|---|---|---|---|---|---|---|---|
| 2021 | Deducted | 10% of the price | 20% of the price | Deducted | Deducted | 10% | 10% |
| 2022 | Deducted | 10% of the price | 20% of the price | Deducted | Deducted | 10% | 10% |
| 2023 | Deducted | 10% of the price | 20% of the price | Deducted | Deducted | 10% | 10% |
| 2024 | Deducted | 10% of the price | 20% of the price | Deducted | Deducted | 10% | 10% |
| 2025 | Deducted | 10% of the price | 20% of the price | Deducted | Deducted | Deducted | 1% |
| 2026 | Deducted | 10% of the price | 20% of the price | Deducted | Deducted | Deducted | 1% |
| 2027 (planning) | Deducted | 10% of the price | 20% of the price | Deducted | Deducted | Deducted | 1% |
Which sales are taxed and which are deducted income
| Rule | Value |
|---|---|
| Securities (listed shares, funds and ETFs, unlisted participation) | Deducted (non-taxable) income under article 149(1)(2) and (3) |
| Construction-linked participation inside the acquisition year plus three tax years | 10% (article 149(2)(3), article 150(15)) |
| Property: the tax base | The alienation income (the sale price), not the profit |
| Property sold to a company, an individual entrepreneur or a notary | 10% of the price (article 150(9)) |
| Property sold to a private individual who is not in business | Deducted (article 147(1)(16)) |
| A natural-person developer's sale of a building or apartment | 20% of the price, with an 80% cadastral-value floor (articles 145(1)(1), 150(11)) |
| Land | Deducted whatever its designated purpose (article 147(1)(38)) |
| Crypto | Deducted from 1 January 2025 (article 147(1)(16.1)); 10% property reading before 2025; NFTs and validation rewards 1% (article 150(9.1)) |
| Vehicle to a VAT payer holding a trade-in licence; gold to a gold-market agent | Deducted (articles 147(1)(41), 147(1)(39)) |
| Losses | No individual loss pool, no netting across disposals and no carry-forward |
| Declaration and payment | Annual income declaration due 1 July of the following year (article 156(4), (4.1)) |
Tables are built from the source records retrieved 2026-09-19; each links back to the authority page above. For 2021 to 2024 the calculator reads a crypto sale under the property rule at 10%; land is always deducted.
Selling in Armenia
Armenian tax on property, shares and crypto: questions sellers ask
What is the income tax rate in Armenia?
The general rate is a flat 20%, set by article 150(1) of the Tax Code, and it applies to salary and to any income without a rate of its own. A sale has its own rule: property sold to a business pays 10% of the price, a developer's sale pays 20%, and shares, land, private-buyer sales and ordinary crypto are deducted.
Does Armenia have a capital gains tax?
No. Sales are taxed through the personal income tax, and the treatment depends on the asset and the buyer. Shares, funds and unlisted stakes are deducted under article 149, land under article 147(1)(38), and ordinary crypto since 1 January 2025. Property sold to a company, an individual entrepreneur or a notary pays 10% of the price.
How much tax do you pay when you sell an apartment in Armenia?
Sold to a company, an individual entrepreneur or a notary, 10% of the sale price, whatever the profit: a flat sold for AMD 60,000,000 pays AMD 6,000,000. Sold to a private individual, nothing. A developer selling to a private individual pays 20% of the price, or of 80% of the cadastral value when that is higher.
Do you pay tax on shares in Armenia?
Not on the gain. Article 149(1)(2) and (3) deducts income from selling shares, fund units and unlisted participation, with no holding period. A stake formed through a construction and sold within the acquisition year plus 3 tax years pays 10%. Dividends are separate and pay 5% unless the stock is listed in Armenia.
Is crypto taxed in Armenia?
Selling ordinary crypto is deducted income since 1 January 2025 under article 147(1)(16.1). NFTs and crypto created as a reward for validating transactions or maintaining a ledger pay 1%. In the example a AMD 13,000,000 gain pays AMD 0 in 2026.
What tax does a developer pay on selling apartments in Armenia?
20% of the price under article 150(11), and the price counted is at least 80% of the cadastral value (article 145(1)(1)). In the example an apartment sold for AMD 70,000,000 against a AMD 100,000,000 cadastral value pays AMD 16,000,000.
Can a loss on a sale be deducted in Armenia?
No. Gains on shares, funds and ordinary crypto are deducted, so their losses reduce nothing, and property sold to a business is taxed on the price, so a loss changes nothing.
When is the Armenian income tax declaration due?
The declaration runs from 2 March to 1 July of the year after the sale, and the tax is due by 1 July. Sales made in 2026 are due by 1 July 2027. The tax authority completes the declaration first, and a completed declaration you leave alone counts as submitted.
Verification
References
Sources
The pages the figures on this page were read from.
Tax Code of the Republic of Armenia
Used for capital gains tax, income tax and VAT and GST. Retrieved .
Official links
The country's tax authority and its capital gains tax pages.
State Revenue Committee of the Republic of Armenia
Tax authority. Checked .
Tax Code of the Republic of Armenia
Capital gains tax. Checked .
How the calculator works and is tested
Every rate, threshold and date on this page comes from 21 dated records covering 2021 to 2027. Each record names the page it was read from and the day it was retrieved. The calculator applies the record in force on the day of each sale and stops with an error when none is, instead of estimating.
Sales are matched to purchases by the country's own rule: first in, first out by default, the UK's same-day, 30-day and Section 104 rules, and Canada's average cost. A sale not fully valued in the country's currency is flagged and left out of the result, never guessed.
Every country has a calculation engine with its own test file of worked cases. Where a calculator ships sample exports, tests run them through the import adapters and check that each file is detected and read correctly. Type checks, linting, unit tests and backend tests run on every change, and English page renders are compared with stored snapshots.